
Neuroplastičnost: kako preuzeti kontrolu nad svojim mozgom
Ako te zanima kako poboljšati rad svog mozga, kako lakše i bolje učiti nove vještine i navike i, najvažnije, kako ne raditi protiv sebe, imamo nešto za tebe. U ovom članku govorimo o neuroplastičnosti, sposobnosti mozga da se razvija i mijenja, na koju možeš utjecati i tako poboljšati rad svoga mozga.
OTVORENE PRIJAVE ZA NOVI CIKLUS EDUKACIJE 25./26.
Neuroplastičnost i nutricionizam: kako prehrana i navike oblikuju mozak | Inkubator izvrsnosti - 30% popusta!
Što je neuroplastičnost?
Do nedavno se općenito smatralo da se mozak, pogotovo mozak odrasle osobe, ne može mijenjati ni obnavljati. No znanost nam danas pokazuje da je to ipak moguće. Neuroplastičnost je sposobnost mozga da se prilagođava i mijenja sukladno uvjetima i novim iskustvima. Bez obzira na dob, iskustva i navike, zahvaljujući mehanizmu neuroplastičnosti tvoj mozak praktički uvijek ima mogućnost učenja novih obrazaca, stvaranja novih navika, pa čak i oporavljanja nakon oštećenja.
Ljudski mozak sastoji se od milijardi neurona, živčanih stanica, koji neprestano međusobno komuniciraju i prenose informacije pomoću neurotransmitera. Ta komunikacijska mreža omogućava sve moždane funkcije. Neuroplastičnost je sposobnost živčanih stanica i njihovih međusobnih veza da se s vremenom mijenjaju i prilagođavaju. To može biti rezultat izvanjskih okolnosti, ali “vježbanja” mozga da uči, pamti i stvara nove obrasce ponašanja. Pravilo je jednostavno: neuronske veze koje se više koriste postaju snažnije i dominantne, a one koje se manje koriste postaju slabije i nestaju. Te promjene rezultiraju i promjenom strukture mozga. Na primjer, ako si dešnjak, dio motornog korteksa lijeve polutke mozga koji upravlja tvojom desnom rukom značajno je veći od dijela motornog korteksa desne polutke koji upravlja tvojom lijevom rukom.
Zato možemo reći da su dva glavna “sastojka” neuroplastičnosti:
- intenzitet (koliko aktivno mozak sudjeluje u obavljanju određene funkcije)
- repetitivnost (koliko često mozak vrši istu funkciju)

Kako funkcionira neuroplastičnost?
Različiti izvanjski i unutarnji podražaji utječu na mehanizam neuroplastičnosti, kao što su: ozljede, stres, tjelesna aktivnost i učenje – posebno učenje neke nove vještine, poput novog jezika ili glazbenog instrumenta. No fokusirajmo se ovdje na načine kako sam/a možeš utjecati na plastičnost svog mozga. Za početak je važno imati ispravnu percepciju toga koliko zapravo ti kontroliraš svoj mozak, a ne samo on tebe.
Kad god o nečemu razmišljaš, obavljaš neki posao, želiš nešto, osjećaš nešto, svome mozgu daješ uputu da tu istu radnju pamti i uči kako je obavljati brže, učinkovitije i sa što manje truda. Vrijedi i obratno. Kad nešto prestaneš činiti i ponavljati ili prestaneš razmišljati na određen način, neuronske veze u tvom mozgu povezane s tim radnjama postaju sve slabije i slabije.
Svojim ponašanjem možeš ubrzati ili usporiti starenje svog mozga. Navike koje općenito najviše guše normalno funkcioniranje mozga, ali i kreativnost, kritičko mišljenje jesu: pretilost, loša prehrana, pušenje, konzumiranje alkohola, manjak tjelovježbe itd. Mnoge od tih stvari obično promatramo u odnosu na srčane i plućne bolesti koje mogu prouzrokovati. Ali takve navike itekako kvare tvoj mozak i čine ga slabijim, sporijim i starijim.

Primjena neuroplastičnosti
Evo nekoliko važnih stvari na koje trebaš paziti ako pomoću neuroplastičnosti želiš poboljšati kvalitetu i dugovječnost svog mozga:
- Tjelovježba i prehrana. Iako je mozak samo manji dio tvog tijela, stanje ostatka tvog organizma izuzetno je važno za rad mozga. Na primjer, pretilost može čak uzrokovati značajno smanjenje veličine mozga, a posebno onih dijelova mozga koji su zaslužni za učenje i pamćenje. Ako o tome nisi dosad razmišljao/la, možda je vrijeme da kreneš planirati: kako se hraniš, koliko vježbaš, koliko odmaraš, koliko spavaš itd.
- Način razmišljanja. Automatske negativne misli nisu povezane samo s depresijom, anksioznosti i promjenama raspoloženja, nego mogu ozbiljno utjecati i na kvalitetu rada mozga. Negativne misli, poput prekomjerne samokritičnosti i cinizma, crpe resurse mozga i neuronskih mreža i tako izravno narušavaju moždane funkcije poput kritičkog mišljenja, a mogu i povećati rizik od demencije. Na našem blogu možeš čitati o različitim metodama za nošenje s negativnim mislima, poput mindfulnessa i terapije pisanjem.
- Rutina. Način na koji razmišljaš, odluke koje donosiš i tvoje navike oblikuju neuralne mreže u tvom mozgu, koje mogu za njega biti korisne ili štetne. Iako je tvoj mozak “moćan stroj”, da bi usvojio neku promjenu i naučio novi obrazac razmišljanja i ponašanja, često je potrebno određeno vrijeme i ustrajno ponavljanje radnje, jednom riječju – rutina. Zahvaljujući neuroplastičnosti, tvoj mozak se uvijek može promijeniti. Ali što si stariji/a, to ti više treba, vremena, truda i strpljivosti da neku željenu promjenu pretvoriš u rutinu. Na našem blogu možeš čitati o nekim pouzdanim strategijama za razvoj i održavanje navika.
________________
Ako želiš naučiti više o neuroplastičnosti i kako je najbolje primijeniti u svakodnevnom životu, prijavi se na online edukaciju Iskoristi moć neuroplastičnosti.
Još s bloga
Sve objave
Čitanje u svakoj dobi: kako ponovno pronaći vrijeme za knjigu?
Koliko si puta rekao da nemaš vremena za čitanje? Knjiga čeka na polici, ti pogledaš naslovnicu i pomisliš: „Pročitat ću je kad uhvatim malo vremena.
More Than Money: Why Financial Literacy Is a Democratic Competence
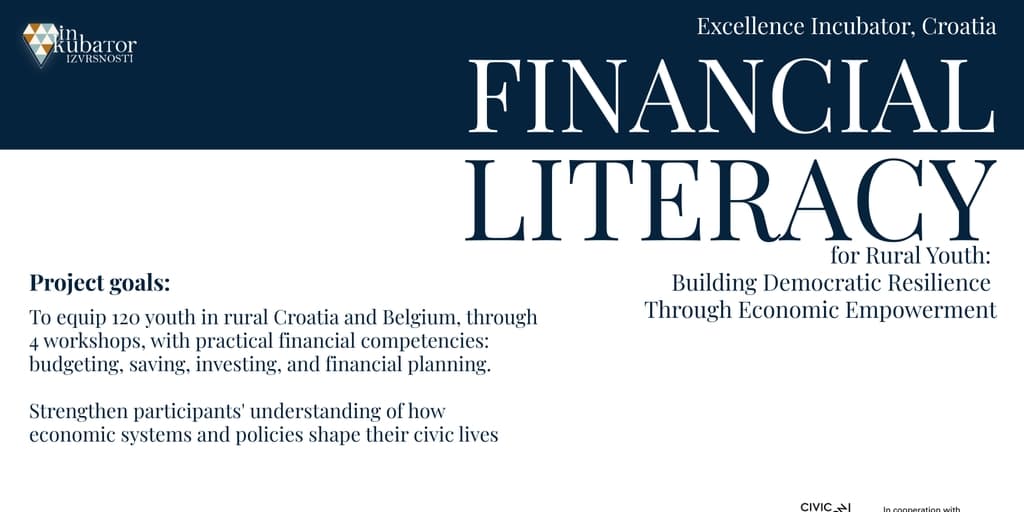
Reflections from the Financial and Economic Literacy NECE Lab, Vienna, 27–28 April 2026 When we talk about financial literacy, most people picture budgeting apps, savings accounts, and the fine print on a loan agreement. Useful things, but a narrow picture. Increasingly, educators, researchers, and policymakers across Europe are making a bigger claim: understanding money is not only a personal survival skill. It is a foundation of active citizenship and democratic resilience. That claim was the beating heart of the Financial and Economic Literacy NECE Lab in Vienna, a two-day gathering hosted by THE CIVICS Innovation Hub together with Znanje na djelu and the Erste Financial Life Park (FLiP), with the support of ERSTE Foundation. We were proud to be part of it, having Magdalena Basić Alando actively participate and present our own project, Financial Literacy for Rural Youth, and learning alongside practitioners from across the continent. This post pulls together what the research actually says, and what we saw play out in the room. The problem: too many young people can't apply what they know Start with the evidence. In the OECD's most recent international assessment of 15-year-olds, released in 2024, the picture is sobering: across the 14 OECD countries assessed, 18% of students on average do not have basic proficiency in financial literacy, meaning they cannot apply their knowledge to real-life situations involving financial decisions. The gap is not evenly distributed. Socio-economically disadvantaged students are over-represented among low performers, which risks entrenching inequality as those students become adults. In other words, the young people who most need economic confidence are the ones least likely to be given it — a pattern that maps neatly onto who feels shut out of public life more broadly. There is a hopeful flip side. Financial literacy and positive financial behaviour are linked: students with stronger skills behave more responsibly with money and are more forward-looking, with high performers markedly more likely than low performers to save. Skills, attitudes, and behaviour move together — which is exactly why how we teach matters as much as what we teach. The bigger claim: financial literacy feeds democratic participation Here is where the Vienna conversation went beyond personal finance. One of the Lab's expert speakers was Anna Lo Prete of the University of Turin, whose research sits right at this intersection — and whose work is among the clearest evidence we have on the question. Lo Prete's cross-country analysis documents a positive association between political participation — measured by the number of citizens voting in national elections — and the awareness of the trade-offs behind private and public decisions that basic financial education captures. Crucially, this is not just correlation dressed up: empirical models that control for a large set of other determinants of voter turnout indicate that financial literacy continues to have a positive and causal impact on electoral participation. Why would that be? The logic is intuitive once you see it. Understanding some economics and finance helps citizens grasp the reasons behind public intervention and weigh the pros and cons of policy proposals and agendas. A voter who understands taxation, public budgets, inflation, and debt is simply better equipped to evaluate the promises on a ballot — and harder to mislead. The catch: financial literacy alone isn't enough It would be too easy to conclude "teach kids about compound interest and democracy takes care of itself." The research is more demanding than that — and this nuance came up repeatedly in Vienna's group work. A recurring critique in the academic literature is that much mainstream financial education quietly frames citizens as consumers rather than participants. One influential analysis argues that dominant financial literacy programmes can end up promoting a limited, consumerist form of civic engagement, and that what is really needed is a critical, emancipatory civic financial literacy for an engaged citizenry able to extend and protect more robust conceptions of freedom and democracy. Scholars working on integrative economic education put the point sharply: financial literacy without civic competence remains a merely reactive skill rather than a source of genuine political agency, which is why financial literacy and civic competences should be understood as parts of a single integrative concept of economic education. The two only reach their full value when taught together — money knowledge that can read the system, not just cope with it. Europe is building the scaffolding None of this is happening in a vacuum. The policy architecture is catching up with the research. In 2023 the European Commission and the OECD jointly published a Financial Competence Framework for Children and Youth in the European Union. It is not only about interest rates and risk: alongside the four core content areas — money and transactions, planning and managing finances, risk and reward, and the financial landscape — the framework deliberately integrates cross-cutting dimensions including digital finance, sustainable finance, entrepreneurship, and citizenship. Citizenship is written into the framework by design. On the civic side, the Council of Europe's Reference Framework of Competences for Democratic Culture exists precisely to equip young people with the competences needed to defend and promote human rights, democracy and the rule of law, to act as active citizens, and to live peacefully together with others. Read the two frameworks side by side and the overlap is obvious: critical thinking, informed decision-making, and the confidence to participate. What this looks like in practice: rural youth and economic autonomy This is the gap our own project set out to close, and the reason we were presenting it in Vienna. Financial Literacy for Rural Youth: Building Democratic Resilience Through Economic Empowerment merges financial and civic education for an audience usually left out of both: young people in rural areas, who are systematically underrepresented in programmes that tend to be urban-centred. Working with our partners, the project equips rural GenZ participants in Croatia and Belgium with practical competences: budgeting, saving, investing, planning; through gamified, peer-to-peer, blended learning adapted to rural digital realities. But the design goes a step past personal finance, exactly along the lines the research recommends. Participants learn to analyse economic policies, financial products, and media narratives about money, so they can resist manipulation and make informed civic choices. The premise is that economic dependency and exclusion are themselves barriers to democratic participation, and that when young people understand how taxation, public budgets, and economic policy shape their own lives, they engage more meaningfully in democratic processes. A transnational peer exchange between Croatian and Belgian participants adds a cross-cultural, shared-European dimension, a small counterweight to the polarisation that tends to follow economic marginalisation. The pilot trainings in Croatia are already complete, with workshops in Belgium still ahead. And the methodology is being built to outlast the project and be shared amongst all stakeholders. Where the formal and non-formal worlds meet If there was one moment in Vienna that made the abstract concrete, it was the guided tour of the Erste Financial Life Park (FLiP), FLiP turns financial education into something you can walk through and touch: interactive stations where visitors make real-feeling budgeting decisions and immediately see the consequences. It is a vivid rebuttal to the idea that money education has to be dry. A theme the NECE Lab kept returning to, and one the research underlines, is the relationship between formal schooling and non-formal education. Classrooms provide reach and legitimacy; non-formal initiatives like ours provide the agility to reach underserved groups, experiment with gamified and peer-led methods, and adapt fast. The most promising path forward is not one or the other, but connective tissue between them: school systems that borrow the energy of non-formal approaches, and civic organisations whose toolkits can be picked up and used inside classrooms. The takeaway The case made in Vienna, and backed by the evidence, is straightforward but consequential. Financial literacy is not merely about helping individuals stay solvent. Done well, paired with civic competence rather than reduced to consumer advice, it strengthens people's capacity to understand the systems they live in, to resist manipulation, and to participate in the democratic decisions that shape their economic lives. In an era of rising costs, growing inequality, and declining trust in institutions, that capacity is not a luxury. It is infrastructure for democracy. We left Vienna grateful to all speakers for the intellectual grounding; to our fellow educators for the knowledge exchange and the good company; to the organisers: THE CIVICS Innovation Hub, Znanje na djelu, Erste Financial Life Park, and ERSTE Foundation, FLiP centre. The next chapter is being written in rural classrooms and community halls across Europe. We're glad to be part of it. Sources OECD (2024), PISA 2022 Results (Volume IV): How Financially Smart Are Students?, OECD Publishing. Lo Prete, A. (2024), Political participation and financial education: Understanding personal and collective trade-offs for a better citizenship, Economics Letters / ScienceDirect. Lo Prete, A., Financial education: From better personal finance to improved citizenship, Journal of Financial Literacy and Wellbeing, Cambridge Core. Arthur, C. (2012), Financial Literacy Education for Citizens: What Kind of Responsibility, Equality and Engagement?, Citizenship, Social and Economics Education (SAGE). Integrative Economic Education to Combine Citizenship Education and Financial Literacy (ResearchGate). European Union / OECD (2023), Financial Competence Framework for Children and Youth in the European Union, OECD Publishing. Council of Europe, Reference Framework of Competences for Democratic Culture (RFCDC).
Životni skript: zašto ponavljaš iste obrasce i kako ih promijeniti?
Jesi li ikad primijetio/la da u različitim vezama završavaš s istim tipom problema? Ili da na poslu uvijek ulazi u istu vrstu sukoba --- bez obzira...
