
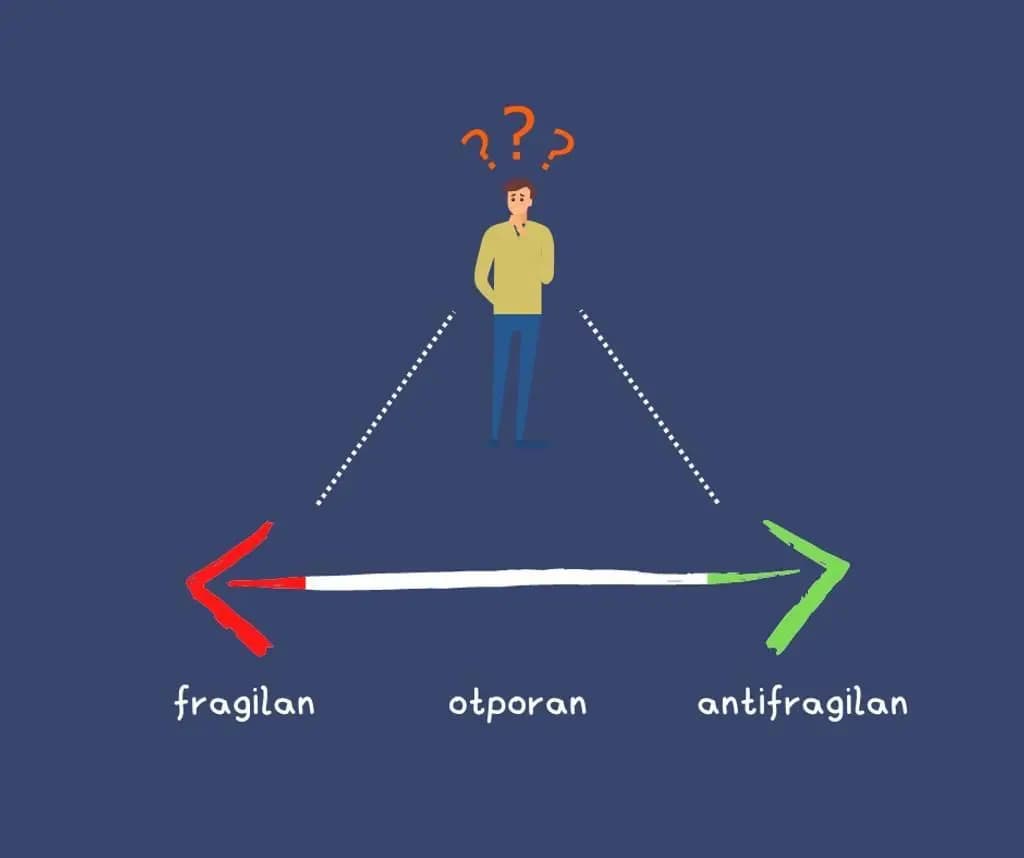
Antifragilnost – bolje od psihološke otpornosti
Kako izgraditi psihološku otpornost u tri koraka? Pet stvari koje moraš znati da bi postao/la psihološki otporan! Top 10 navika psihološki otpornih pojedinaca! Sigurno često nailaziš na takve naslove, a članci te uglavnom razočaraju jer ti ne kažu ništa novo ni korisno. Ovaj je članak drukčiji. U nastavku saznaj više o tome što je psihološka otpornost, koje su prednosti i nedostaci te ideje te postoji li nešto bolje od psihološke otpornosti.
Što je psihološka otpornost?
Danas se o psihološkoj otpornosti govori kao o vrhuncu mentalnog zdravlja. Biti mentalno zdrav značilo bi imati snažan imunitet za sve ono što je psihološki gledano nezdravo, a to najčešće zovemo jednom riječju – stres. Ako možeš izdržati velike količine stresa i ostati smiren u različitim stresnim situacijama, znači da si otporan na stres, odnosno da imaš dobru psihološku otpornost. Ako ti to sve zvuči prejednostavno i neostvarivo, u pravu si.
Naša razmišljanja o stresu, mentalnom zdravlju i psihološkoj otpornosti često su zapravo pogrešna, zato što ne postavljamo neka vrlo jednostavna pitanja: Što je stres? Je li svaki stres nužno loš? Može li stres biti koristan? Što znači biti otporan na nešto? Možemo li uopće biti otporni na stres? Je li to najbolje što možemo?
Odgovor na ta pitanja krije se u relativno novom konceptu u području mentalnog zdravlja, a to je – antifragilnost.
Antifragilnost je bolja od otpornosti. Ono što je otporno odolijeva šokovima i ostaje isto; ono što je antifragilno postaje još bolje.
- Nassim Nicholas Taleb
Što je antifragilnost?
Zamisli da pakiraš kutije za selidbu i u jednu kutiju spremaš vrijedno stakleno posuđe. Što ćeš napisati na takvu kutiju? Vjerojatno nešto kao “Oprez: lomljivo!” ili “Rukovati s oprezom!”. To je zato što su stakleni predmeti baš takvi, lomljivi. Ono što je lomljivo ne voli nikakav “stres”. No što bi bilo suprotno od toga? Vjerojatno misliš da su to sve one kutije na koje nećeš napisati ništa, jer su unutra stvari koje nisu lomljive i s kojima ne treba biti posebno oprezan. Takve stvari su otporne na proces selidbe i uglavnom im se neće dogoditi ništa. Možemo reći da su one “ravnodušne” prema stresu, tj. svejedno im je. Ali postoje li stvari koje baš “vole” da se s njima postupa neoprezno? Možeš li zamisliti da na jednu kutiju napišeš “Oprez: obavezno lupati!”? Možda ne posjeduješ ništa takvo, ali takve stvari itekako postoje. Za njih kažemo da su antifragilne.
Riječ antifragilnost tek je nedavno skovao američki autor Nassim Nicholas Taleb, a ona doslovno znači “suprotno od onoga što je fragilno”. Kao što pokazuje primjer s kutijom, suprotno od fragilnog ili lomljivog nije nešto neslomljivo ni otporno. Ako je fragilno ono što ne voli stres, onda je antifragilno ono što “voli stres”.
Možda ti na prvu zvuči neobično da postoji nešto takvo što može imati koristi od stresa, ali takve su stvari posvuda oko tebe. Zapravo, i ti si takva stvar.

Kako funkcionira antifragilnost?
Pitaš se, kako možeš imati koristi od stresa? Dobro pitanje. No najprije moramo dobro definirati stres. Stres je posljedica naše reakcije na potencijalno sve što na nas može imati nepoželjan utjecaj, kao što su: iznenadni neugodni događaji, promjene, neugodne osobe, bol, šok, udar, pad, izazov, neuspjeh, gubitak, opasnost, neizvjesnost, vrijeme itd. Psihološki gledano, sve su to oblici stresa. Antifragilno je ono što može imati koristi od svega toga.
Evo nekoliko jednostavnih primjera iz života u kojima se jasno vidi zakon antifragilnosti:
- psihologija: Kod poremećaja kao što je agorafobija (strah od otvorenih prostora) u bihevioralnoj terapiji primjenjuje se tzv. terapija izlaganjem, u kojoj se pacijenta u malim, ali sve većim dozama postupno izlaže onome čega se boji. U takvim situacijama, tehnika je izuzetno uspješna, a cilj joj nije samo otpornost na strah, nego prevladavanje straha i razvijanje vještina s kojima se osoba nakon terapije može normalno suočiti s onim od čega je prije strahovala. O sličnim tehnikama pisali smo ranije u tekstu o stoicizmu.
- tjelovježba: Ako želimo postati fizički snažniji, to nećemo postići dizanjem što lakših utega i izbjegavanjem umora, nego postizanjem optimalnog opterećenja mišića, a to često znači vježbanje s maksimalnom težinom s kojom možemo raditi u određenom formatu vježbe. To naravno ovisno o vježbi, skupini mišića i našoj tjelesnoj spremnosti, ali načelo je univerzalno primjenjivo. Drugim riječima, da bi rasli, našim mišićima potreban je “šok”.
- znanost: O znanosti i tehnologiji često razmišljamo samo u smislu znanstvenih otkrića, ali zaboravljamo da svakom napretku prethodi niz neuspjelih znanstvenih teorija i eksperimenata. No svaki neuspjeh potiče nova istraživanja i rađa nove teorije, ideje i rješenja. Pogreške, neuspjesi i porazi nužan su sastojak svakog znanstvenog i tehnološkog postignuća. Bez takvih padova i neuspjeha znanost ne bi bila moguća.
- vještine: Antifragilnost trebamo i za razvoj bilo koje vještine. To pogotovo vrijedi kad pokušavamo usvojiti vještine koje nam prirodno “ne leže”. Na primjer, ako ne voliš javne nastupe ili bilo kakvo izlaganje pred drugima, zadnje što trebaš činiti jest da po svaku cijenu izbjegavaš takve situacije. To je siguran put da zauvijek ostaneš fragilan/a. Umjesto toga, jedini način da pobijediš tu svoju slabost jest da se namjerno okušaš u tome, čak i ako ti to stvara nelagodu i čak i ako znaš da ćeš biti loš/a. Prvi put možda i hoćeš, možda i drugi i treći. Ali nakon nekoliko ponavljanja i prije nego što i primijetiš, na osnovu samog ponavljanja istog, već ćeš imati neke stečene vještine zbog kojih će ti ta stvar svaki put biti sve lakša i lakša.
- djeca: Djeca su zanimljiv spoj fragilnosti i antifragilnosti. Ona su u mnogo čemu ovisna o odraslima i u puno stvari traže konstantnu brigu i zaštitu. Ipak, ako djecu previše zaštitimo, izlažemo ih opasnosti da u nekim aspektima svog razvoja "zakržljaju". To dugoročno za njih može stvoriti ozbilje posljedice. Na primjer, ako im ograničavamo da sami istražuju svoju okolinu, lišavamo ih mogućnosti da od ranih dana uče iz vlastitog iskustva i pogrešaka; ako im uskraćujemo kontakt s drugom djecom, kočimo rani razvoj njihovih društvenih vještina; ako ih nastojimo unaprijed izolirati od svake bolesti ili nepoznatih namirnica, narušavamo prirodni rad njihova imuniteta i izlažemo ih opasnosti da upravo zbog toga budu posebno podložni određenim bolestima ili alergijama.
Važno: antifragilnost ovisi o kontekstu
Osim što je kao načelo primjenjiva u različitim životnim kontekstima, antifragilnost pomaže ti i bolje razumjeti pojmove kao što su stres, psihološka otpornost i mentalno zdravlje. Ako razumiješ načelo antifragilnosti, onda znaš da psihološka otpornost zapravo nije nužno neki ideal kojem trebaš težiti. Tvoj cilj trebala bi biti antifragilost. Cilj je da svoje "stresore" možeš pretvorimo u nešto korisno i nešto što će ti pomoći da postaneš snažnija verzija sebe.
Važno je znati da je antifragilnost ograničeno svojstvo i da ona uvijek ovisi o kontekstu. Količina određenog oblika stresa može za tebe imati veću ili manju korist ovisno o situaciji. Ali to ne znači da si neograničeno otporan/a na svaki stres.
Stoga je važno da dobro poznaješ sebe i svoje slabosti, ali i da budeš uvijek otvoren/a za situacije koje ti predstavljaju izazov. Zato što samo tako možeš rasti i pomicati svoje granice i zato što ti to možeš.
_________________________
Želiš znati više o antifragilnosti i kako je ostvariti u svom životu? Na pravom si mjestu!
Pretplati se na edukaciju Stres pod kontrolom i nauči sve o antifragilnosti i mnogim drugim psihološkim metodama i alatima koji će ti pomoći da postaneš snažnija i sretnija verzija sebe.
Još s bloga
Sve objave
Čitanje u svakoj dobi: kako ponovno pronaći vrijeme za knjigu?
Koliko si puta rekao da nemaš vremena za čitanje? Knjiga čeka na polici, ti pogledaš naslovnicu i pomisliš: „Pročitat ću je kad uhvatim malo vremena.
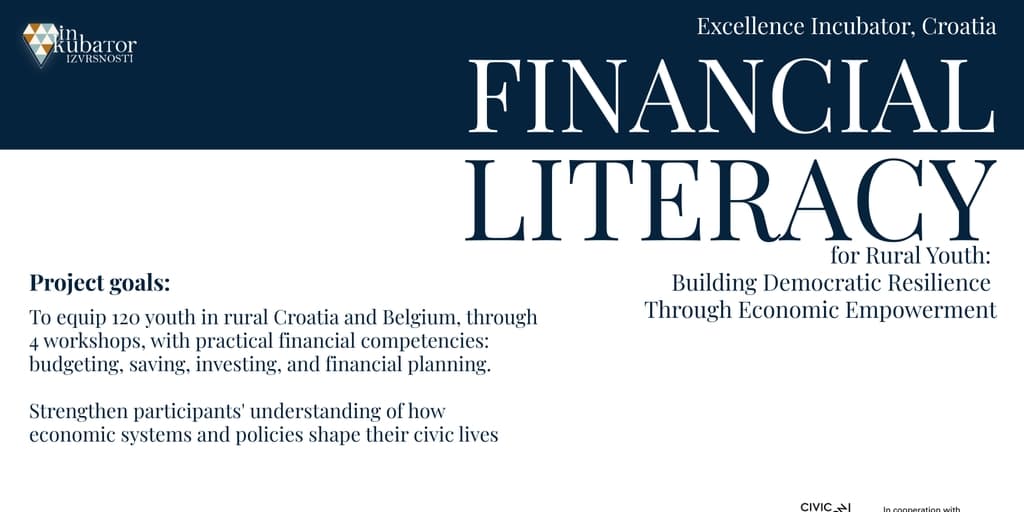
More Than Money: Why Financial Literacy Is a Democratic Competence
Reflections from the Financial and Economic Literacy NECE Lab, Vienna, 27–28 April 2026 When we talk about financial literacy, most people picture budgeting apps, savings accounts, and the fine print on a loan agreement. Useful things, but a narrow picture. Increasingly, educators, researchers, and policymakers across Europe are making a bigger claim: understanding money is not only a personal survival skill. It is a foundation of active citizenship and democratic resilience. That claim was the beating heart of the Financial and Economic Literacy NECE Lab in Vienna, a two-day gathering hosted by THE CIVICS Innovation Hub together with Znanje na djelu and the Erste Financial Life Park (FLiP), with the support of ERSTE Foundation. We were proud to be part of it, having Magdalena Basić Alando actively participate and present our own project, Financial Literacy for Rural Youth, and learning alongside practitioners from across the continent. This post pulls together what the research actually says, and what we saw play out in the room. The problem: too many young people can't apply what they know Start with the evidence. In the OECD's most recent international assessment of 15-year-olds, released in 2024, the picture is sobering: across the 14 OECD countries assessed, 18% of students on average do not have basic proficiency in financial literacy, meaning they cannot apply their knowledge to real-life situations involving financial decisions. The gap is not evenly distributed. Socio-economically disadvantaged students are over-represented among low performers, which risks entrenching inequality as those students become adults. In other words, the young people who most need economic confidence are the ones least likely to be given it — a pattern that maps neatly onto who feels shut out of public life more broadly. There is a hopeful flip side. Financial literacy and positive financial behaviour are linked: students with stronger skills behave more responsibly with money and are more forward-looking, with high performers markedly more likely than low performers to save. Skills, attitudes, and behaviour move together — which is exactly why how we teach matters as much as what we teach. The bigger claim: financial literacy feeds democratic participation Here is where the Vienna conversation went beyond personal finance. One of the Lab's expert speakers was Anna Lo Prete of the University of Turin, whose research sits right at this intersection — and whose work is among the clearest evidence we have on the question. Lo Prete's cross-country analysis documents a positive association between political participation — measured by the number of citizens voting in national elections — and the awareness of the trade-offs behind private and public decisions that basic financial education captures. Crucially, this is not just correlation dressed up: empirical models that control for a large set of other determinants of voter turnout indicate that financial literacy continues to have a positive and causal impact on electoral participation. Why would that be? The logic is intuitive once you see it. Understanding some economics and finance helps citizens grasp the reasons behind public intervention and weigh the pros and cons of policy proposals and agendas. A voter who understands taxation, public budgets, inflation, and debt is simply better equipped to evaluate the promises on a ballot — and harder to mislead. The catch: financial literacy alone isn't enough It would be too easy to conclude "teach kids about compound interest and democracy takes care of itself." The research is more demanding than that — and this nuance came up repeatedly in Vienna's group work. A recurring critique in the academic literature is that much mainstream financial education quietly frames citizens as consumers rather than participants. One influential analysis argues that dominant financial literacy programmes can end up promoting a limited, consumerist form of civic engagement, and that what is really needed is a critical, emancipatory civic financial literacy for an engaged citizenry able to extend and protect more robust conceptions of freedom and democracy. Scholars working on integrative economic education put the point sharply: financial literacy without civic competence remains a merely reactive skill rather than a source of genuine political agency, which is why financial literacy and civic competences should be understood as parts of a single integrative concept of economic education. The two only reach their full value when taught together — money knowledge that can read the system, not just cope with it. Europe is building the scaffolding None of this is happening in a vacuum. The policy architecture is catching up with the research. In 2023 the European Commission and the OECD jointly published a Financial Competence Framework for Children and Youth in the European Union. It is not only about interest rates and risk: alongside the four core content areas — money and transactions, planning and managing finances, risk and reward, and the financial landscape — the framework deliberately integrates cross-cutting dimensions including digital finance, sustainable finance, entrepreneurship, and citizenship. Citizenship is written into the framework by design. On the civic side, the Council of Europe's Reference Framework of Competences for Democratic Culture exists precisely to equip young people with the competences needed to defend and promote human rights, democracy and the rule of law, to act as active citizens, and to live peacefully together with others. Read the two frameworks side by side and the overlap is obvious: critical thinking, informed decision-making, and the confidence to participate. What this looks like in practice: rural youth and economic autonomy This is the gap our own project set out to close, and the reason we were presenting it in Vienna. Financial Literacy for Rural Youth: Building Democratic Resilience Through Economic Empowerment merges financial and civic education for an audience usually left out of both: young people in rural areas, who are systematically underrepresented in programmes that tend to be urban-centred. Working with our partners, the project equips rural GenZ participants in Croatia and Belgium with practical competences: budgeting, saving, investing, planning; through gamified, peer-to-peer, blended learning adapted to rural digital realities. But the design goes a step past personal finance, exactly along the lines the research recommends. Participants learn to analyse economic policies, financial products, and media narratives about money, so they can resist manipulation and make informed civic choices. The premise is that economic dependency and exclusion are themselves barriers to democratic participation, and that when young people understand how taxation, public budgets, and economic policy shape their own lives, they engage more meaningfully in democratic processes. A transnational peer exchange between Croatian and Belgian participants adds a cross-cultural, shared-European dimension, a small counterweight to the polarisation that tends to follow economic marginalisation. The pilot trainings in Croatia are already complete, with workshops in Belgium still ahead. And the methodology is being built to outlast the project and be shared amongst all stakeholders. Where the formal and non-formal worlds meet If there was one moment in Vienna that made the abstract concrete, it was the guided tour of the Erste Financial Life Park (FLiP), FLiP turns financial education into something you can walk through and touch: interactive stations where visitors make real-feeling budgeting decisions and immediately see the consequences. It is a vivid rebuttal to the idea that money education has to be dry. A theme the NECE Lab kept returning to, and one the research underlines, is the relationship between formal schooling and non-formal education. Classrooms provide reach and legitimacy; non-formal initiatives like ours provide the agility to reach underserved groups, experiment with gamified and peer-led methods, and adapt fast. The most promising path forward is not one or the other, but connective tissue between them: school systems that borrow the energy of non-formal approaches, and civic organisations whose toolkits can be picked up and used inside classrooms. The takeaway The case made in Vienna, and backed by the evidence, is straightforward but consequential. Financial literacy is not merely about helping individuals stay solvent. Done well, paired with civic competence rather than reduced to consumer advice, it strengthens people's capacity to understand the systems they live in, to resist manipulation, and to participate in the democratic decisions that shape their economic lives. In an era of rising costs, growing inequality, and declining trust in institutions, that capacity is not a luxury. It is infrastructure for democracy. We left Vienna grateful to all speakers for the intellectual grounding; to our fellow educators for the knowledge exchange and the good company; to the organisers: THE CIVICS Innovation Hub, Znanje na djelu, Erste Financial Life Park, and ERSTE Foundation, FLiP centre. The next chapter is being written in rural classrooms and community halls across Europe. We're glad to be part of it. Sources OECD (2024), PISA 2022 Results (Volume IV): How Financially Smart Are Students?, OECD Publishing. Lo Prete, A. (2024), Political participation and financial education: Understanding personal and collective trade-offs for a better citizenship, Economics Letters / ScienceDirect. Lo Prete, A., Financial education: From better personal finance to improved citizenship, Journal of Financial Literacy and Wellbeing, Cambridge Core. Arthur, C. (2012), Financial Literacy Education for Citizens: What Kind of Responsibility, Equality and Engagement?, Citizenship, Social and Economics Education (SAGE). Integrative Economic Education to Combine Citizenship Education and Financial Literacy (ResearchGate). European Union / OECD (2023), Financial Competence Framework for Children and Youth in the European Union, OECD Publishing. Council of Europe, Reference Framework of Competences for Democratic Culture (RFCDC).
Životni skript: zašto ponavljaš iste obrasce i kako ih promijeniti?
Jesi li ikad primijetio/la da u različitim vezama završavaš s istim tipom problema? Ili da na poslu uvijek ulazi u istu vrstu sukoba --- bez obzira...
