
Kako povećati samopouzdanje: 3 najbolje metode
 Kata Živković6 min čitanja
U čemu je tajna uvijek samouvjerenih, pozitivnih i neustrašivih ljudi koji svojim osmijehom osvajaju srca (i džepove) drugih? Je li to prirodan talent, gluma ili nešto treće?
Ako je samopouzdanje vještina, onda njome može ovladati svatko od nas, ali ako je to stvar urođenog talenta, stvari idu u korist onih koje je “majka priroda” nagradila.
U nastavku ti donosimo, prvo, dobre vijesti, a nakon toga 3 najbolje metode kojima ćeš povećati samopouzdanje.
Samopouzdanje je stvar vježbe
Krećemo odmah s dobrim vijestima. Samopouzdanje se da izvježbati.
APA definira samopouzdanje kao povjerenje u vlastitu sposobnost, kvalitete, mogućnost prosudbe i donošenja odluka.
Sigurno ti se događa da si u nekom području koje ti više leži, u čemu imaš više iskustva i sl, puno samopouzdaniji/a nego u nečem drugom.
Npr: javni nastup/poslovne prezentacije i sl. ti ne predstavljaju nikakav strah i to voliš raditi sa zadovoljstvom, ali kada bi trebao/la otputovati sam/a u neku drugu državu na tjedan dana, nastupa osjećaj bespomoćnosti.
To su dvije različite situacije tijekom kojih se naša razina samopouzdanja mijenja.
Dakle, samopouzdanje može biti vezano uz tvoj opći osjećaj sigurnosti i kontrole u životu, a može biti povezano uz određene situacije.
Bez obzira na kojoj je razini naše samopouzdanje sada postoje metode kojima ga možemo značajno povećati.
U nastavku donosimo 3 najbolje metode za povećanje samopouzdanja, a to su:
- Prvo razmisli o razini samopoštovanja
- Ne uspoređuj se s drugima
- Suoči se sa strahovima
#1 Ako želiš povećati samopouzdanje razmisli prvo o samopoštovanju
Istraživanja pokazuju da nas pogrešna slika o sebi, loša životna iskustva tijekom ranije dobi u određenoj mjeri ograničavaju kada je riječ o samopouzdanju i negativno utječu na našu psihološku dobrobit.
Neugodna životna iskustva mogu smanjiti razinu samopoštovanja, povećati osjećaj krivnje i nesigurnosti.
Iz nedostatka samopoštovanja proizlazi i niža razina samopouzdanja.
Osobe koje imaju nisku razinu samopoštovanja ne znaju postaviti granice u odnosima, češće razmišljaju negativno, lako se obeshrabre kada naiđu na prepreku i dopuštaju drugima da utječu na njihovo raspoloženje.
Takvi će pojedinci češće biti negativni prema sebi i često ih muče negativne misli.
U nastavku su primjeri misli koje često muče osobe s niskom razinom poštovanja. Ako se te misli često ponavljaju, vrte u krug i teško ih se rješavaš riječ je o ruminaciji.
Koliko si puta i ti u sebi ili naglas izrekao/la ove rečenice?
“Glup/a sam, ništa ne radim dobro, svi će mi se smijati, uvijek pogriješim, ja to ne mogu, ne znam to, nikad neću uspjeti i sl…”
Umjesto toga, sljedeći put kada ti se negativne misli krenu motati glavom, a to je najčešće prije nego što moraš odraditi nešto važno ili izložiti sebe nečem novom/nelagodnom, sjeti se da tvoje misli nisu uvijek točne!

Postoji izreka: “Ne vjeruj svemu što misliš.”
Nakon što si osvijestiš da tvoje misli nisu uvijek točne, one polako počinju gubiti moć nad tobom. Tada se pokušaj usmjeriti na one pozitivne misli.
Primjerice, umjesto da sebi kažeš da nikada nećeš uspjeti, da je ovo što si pripremio/la loše, reci sebi da si se potrudio/la, da znaš što radiš, da će sve biti kako treba, da te svako iskustvo uči nečem novom i sl.
Zamjena negativnih misli pozitivnima utječe na razinu ugodnih emocija, oslobađa serotonin i utječe na razinu samopouzdanja.
#2 Ne uspoređuj se s drugima
Uspoređuj se s onim što si ti bio jučer, a ne s onim što je netko drugi danas. Peterson
Navala društvenih mreža i nerealnih kriterija o tome kako bismo trebali izgledati, što bismo trebali odnijenuti, pratimo li trendove ili ne, utječe na razinu samopouzdanja i to uglavnom negativno.
Loš utjecaj društvenih mreža na samopouzdanje posebno je vidljiv kod mladih ljudi.
Paradoksalno je da društvene mreže kod pojedinaca s jedne strane stvaraju nezdravu opsjednutost sobom, a s druge strane iz te “lažne ljubavi prema sebi” proizlazi visoka razina nesigurnosti i potreba da svoju vrijednost potvrdimo lajkovima.
Iako je taj fenomen češći kod mladih, on ne zaobilazi svijet odraslih.
Istraživanja provedena 2018. pokazuju usku povezanost između zavisti i razine samopouzdanja.
Potvrdilo se da što se pojedinci više uspoređuju s drugima, povećava se razina zavisti koju osjećaju, a samim time stvara se sve gori osjećaj nepoštivanja i mržnje prema sebi.
Iako svatko od nas ima prirodnu potrebu uspoređivati se s drugima, u trenucima kada primjetiš da to narušava sliku koju imaš o sebi, demotivira te i obeshrabruje, vrijeme je da nešto promijeniš.
Umjesto da želiš nos kao Ivana, zube kao Matija, talente kao Petar, posao kao Marko, promisli što sve voliš na sebi, na čemu si sve zahvalan/na.
Kao dobar vodič za nošenje sa stresom, koji često proizlazi iz pretjeranog uspoređivanja s drugima, pomaže ti Dnevnik zahvalnosti.
Dnevnik zahvalnosti možeš voditi svaki dan, a značajno će utjecati na tvoju razinu samopouzdanja.
U njega bilježiš sve ono na čemu si danas zahvalan/na, sve dobro što si napravio/la, sve u čemu želiš rasti, potencijale koje vidiš kod sebe. Možeš ga pisati kada želiš, preporučljivo da ga vodiš svaki dan i da odrediš formu pisanja.
Npr: na kraju svakog dana napisat ću 3 stvari na kojima sam danas zahvalan/na, 3 stvari kojima se radujem sutra i 1 stvar koju želim poboljšati.
#3 Suoči se sa strahovima
Postoji izreka: “Don’t do your best, do whatever it takes”.
To znači da ne čekaš trenutak kada će se sve posložiti, nego kreni s onim što imaš i napravi ono što trebaš i možeš.
Da, znam da je jako lijepo u toplini doma, za računalom/ispred TV-a i s poznatim ljudima, nego se izlagati buci, gužvi, nepoznatom i nesigurnom.

Ipak, ako se ne izlažeš nečemu što je nelagodno, a većina početaka je takva, kako uopće misliš rasti?
Većina nas sklona je odgađati stvari dok se sve ne posloži.
Npr: neću održati prezentaciju danas na poslu jer se ne osjećam dovoljno sigurno, jer je danas jugo, ponedjeljak je itd.
Skloni smo tražiti razloge kako bismo izbjegli raditi ono što nas čini nesigurnima.
Kaže se da se onome koji nema tremu ili strah, nije dovoljno stalo. Zato na taj osjećaj straha gledaj kao na nešto sasvim prirodno i kao na znak da ti je stalo.
Istraživanja pokazuju da nam čak mali osjećaj sumnje i nesigurnosti pomaže u izgradnji samopouzdanja.
Trebaš nešto učiniti, ali te strah da ćeš se osramotiti, pogriješiti, zbuniti? Pa što onda? Što je najgore što se može dogoditi? A sad promisli što sve dobro može proizaći iz toga.
Kao što se govornikom ne rađa, nego postaje tako se i tvoje samopouzdanje gradi postepenim izlaganjem strahovima i novim iskustvima.
Sve ove 3 metode već si svjesno ili nesvjesno primjenjivao/la u privatnim i poslovnim izazovima. Ako si uspio/la tada, što te koči da uspiješ opet?
Samopouzdanje proizlazi iz zdrave razine samopoštovanja, ispravne slike o sebi, potrebi da radiš na sebi ne zbog drugih, nego zbog sebe i iz tvoje spremnosti da se suočiš sa svojim strahovima.
Ne zaboravi, ti to možeš!
__________________
Želiš naučiti više o izgradnji samopouzdanja i upoznati se s ključnim temama iz područja psihologije uvjeravanja i komunikacijskih vještina? Na pravom si mjestu.
Pretplati se na edukaciju Psihologija uvjeravanja i otkrij najvažnije teme koje će ti pomoći na putu jačanja samopouzdanj
Još s bloga
Sve objave
Čitanje u svakoj dobi: kako ponovno pronaći vrijeme za knjigu?
Koliko si puta rekao da nemaš vremena za čitanje? Knjiga čeka na polici, ti pogledaš naslovnicu i pomisliš: „Pročitat ću je kad uhvatim malo vremena.
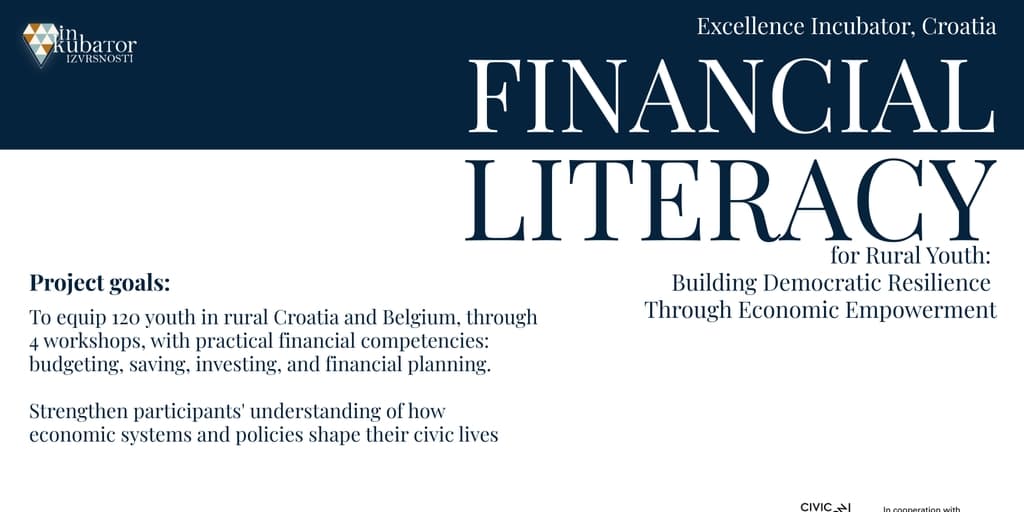
More Than Money: Why Financial Literacy Is a Democratic Competence
Reflections from the Financial and Economic Literacy NECE Lab, Vienna, 27–28 April 2026 When we talk about financial literacy, most people picture budgeting apps, savings accounts, and the fine print on a loan agreement. Useful things, but a narrow picture. Increasingly, educators, researchers, and policymakers across Europe are making a bigger claim: understanding money is not only a personal survival skill. It is a foundation of active citizenship and democratic resilience. That claim was the beating heart of the Financial and Economic Literacy NECE Lab in Vienna, a two-day gathering hosted by THE CIVICS Innovation Hub together with Znanje na djelu and the Erste Financial Life Park (FLiP), with the support of ERSTE Foundation. We were proud to be part of it, having Magdalena Basić Alando actively participate and present our own project, Financial Literacy for Rural Youth, and learning alongside practitioners from across the continent. This post pulls together what the research actually says, and what we saw play out in the room. The problem: too many young people can't apply what they know Start with the evidence. In the OECD's most recent international assessment of 15-year-olds, released in 2024, the picture is sobering: across the 14 OECD countries assessed, 18% of students on average do not have basic proficiency in financial literacy, meaning they cannot apply their knowledge to real-life situations involving financial decisions. The gap is not evenly distributed. Socio-economically disadvantaged students are over-represented among low performers, which risks entrenching inequality as those students become adults. In other words, the young people who most need economic confidence are the ones least likely to be given it — a pattern that maps neatly onto who feels shut out of public life more broadly. There is a hopeful flip side. Financial literacy and positive financial behaviour are linked: students with stronger skills behave more responsibly with money and are more forward-looking, with high performers markedly more likely than low performers to save. Skills, attitudes, and behaviour move together — which is exactly why how we teach matters as much as what we teach. The bigger claim: financial literacy feeds democratic participation Here is where the Vienna conversation went beyond personal finance. One of the Lab's expert speakers was Anna Lo Prete of the University of Turin, whose research sits right at this intersection — and whose work is among the clearest evidence we have on the question. Lo Prete's cross-country analysis documents a positive association between political participation — measured by the number of citizens voting in national elections — and the awareness of the trade-offs behind private and public decisions that basic financial education captures. Crucially, this is not just correlation dressed up: empirical models that control for a large set of other determinants of voter turnout indicate that financial literacy continues to have a positive and causal impact on electoral participation. Why would that be? The logic is intuitive once you see it. Understanding some economics and finance helps citizens grasp the reasons behind public intervention and weigh the pros and cons of policy proposals and agendas. A voter who understands taxation, public budgets, inflation, and debt is simply better equipped to evaluate the promises on a ballot — and harder to mislead. The catch: financial literacy alone isn't enough It would be too easy to conclude "teach kids about compound interest and democracy takes care of itself." The research is more demanding than that — and this nuance came up repeatedly in Vienna's group work. A recurring critique in the academic literature is that much mainstream financial education quietly frames citizens as consumers rather than participants. One influential analysis argues that dominant financial literacy programmes can end up promoting a limited, consumerist form of civic engagement, and that what is really needed is a critical, emancipatory civic financial literacy for an engaged citizenry able to extend and protect more robust conceptions of freedom and democracy. Scholars working on integrative economic education put the point sharply: financial literacy without civic competence remains a merely reactive skill rather than a source of genuine political agency, which is why financial literacy and civic competences should be understood as parts of a single integrative concept of economic education. The two only reach their full value when taught together — money knowledge that can read the system, not just cope with it. Europe is building the scaffolding None of this is happening in a vacuum. The policy architecture is catching up with the research. In 2023 the European Commission and the OECD jointly published a Financial Competence Framework for Children and Youth in the European Union. It is not only about interest rates and risk: alongside the four core content areas — money and transactions, planning and managing finances, risk and reward, and the financial landscape — the framework deliberately integrates cross-cutting dimensions including digital finance, sustainable finance, entrepreneurship, and citizenship. Citizenship is written into the framework by design. On the civic side, the Council of Europe's Reference Framework of Competences for Democratic Culture exists precisely to equip young people with the competences needed to defend and promote human rights, democracy and the rule of law, to act as active citizens, and to live peacefully together with others. Read the two frameworks side by side and the overlap is obvious: critical thinking, informed decision-making, and the confidence to participate. What this looks like in practice: rural youth and economic autonomy This is the gap our own project set out to close, and the reason we were presenting it in Vienna. Financial Literacy for Rural Youth: Building Democratic Resilience Through Economic Empowerment merges financial and civic education for an audience usually left out of both: young people in rural areas, who are systematically underrepresented in programmes that tend to be urban-centred. Working with our partners, the project equips rural GenZ participants in Croatia and Belgium with practical competences: budgeting, saving, investing, planning; through gamified, peer-to-peer, blended learning adapted to rural digital realities. But the design goes a step past personal finance, exactly along the lines the research recommends. Participants learn to analyse economic policies, financial products, and media narratives about money, so they can resist manipulation and make informed civic choices. The premise is that economic dependency and exclusion are themselves barriers to democratic participation, and that when young people understand how taxation, public budgets, and economic policy shape their own lives, they engage more meaningfully in democratic processes. A transnational peer exchange between Croatian and Belgian participants adds a cross-cultural, shared-European dimension, a small counterweight to the polarisation that tends to follow economic marginalisation. The pilot trainings in Croatia are already complete, with workshops in Belgium still ahead. And the methodology is being built to outlast the project and be shared amongst all stakeholders. Where the formal and non-formal worlds meet If there was one moment in Vienna that made the abstract concrete, it was the guided tour of the Erste Financial Life Park (FLiP), FLiP turns financial education into something you can walk through and touch: interactive stations where visitors make real-feeling budgeting decisions and immediately see the consequences. It is a vivid rebuttal to the idea that money education has to be dry. A theme the NECE Lab kept returning to, and one the research underlines, is the relationship between formal schooling and non-formal education. Classrooms provide reach and legitimacy; non-formal initiatives like ours provide the agility to reach underserved groups, experiment with gamified and peer-led methods, and adapt fast. The most promising path forward is not one or the other, but connective tissue between them: school systems that borrow the energy of non-formal approaches, and civic organisations whose toolkits can be picked up and used inside classrooms. The takeaway The case made in Vienna, and backed by the evidence, is straightforward but consequential. Financial literacy is not merely about helping individuals stay solvent. Done well, paired with civic competence rather than reduced to consumer advice, it strengthens people's capacity to understand the systems they live in, to resist manipulation, and to participate in the democratic decisions that shape their economic lives. In an era of rising costs, growing inequality, and declining trust in institutions, that capacity is not a luxury. It is infrastructure for democracy. We left Vienna grateful to all speakers for the intellectual grounding; to our fellow educators for the knowledge exchange and the good company; to the organisers: THE CIVICS Innovation Hub, Znanje na djelu, Erste Financial Life Park, and ERSTE Foundation, FLiP centre. The next chapter is being written in rural classrooms and community halls across Europe. We're glad to be part of it. Sources OECD (2024), PISA 2022 Results (Volume IV): How Financially Smart Are Students?, OECD Publishing. Lo Prete, A. (2024), Political participation and financial education: Understanding personal and collective trade-offs for a better citizenship, Economics Letters / ScienceDirect. Lo Prete, A., Financial education: From better personal finance to improved citizenship, Journal of Financial Literacy and Wellbeing, Cambridge Core. Arthur, C. (2012), Financial Literacy Education for Citizens: What Kind of Responsibility, Equality and Engagement?, Citizenship, Social and Economics Education (SAGE). Integrative Economic Education to Combine Citizenship Education and Financial Literacy (ResearchGate). European Union / OECD (2023), Financial Competence Framework for Children and Youth in the European Union, OECD Publishing. Council of Europe, Reference Framework of Competences for Democratic Culture (RFCDC).
Životni skript: zašto ponavljaš iste obrasce i kako ih promijeniti?
Jesi li ikad primijetio/la da u različitim vezama završavaš s istim tipom problema? Ili da na poslu uvijek ulazi u istu vrstu sukoba --- bez obzira...
